A $100,000 salary is the same number on two offer letters. It can support very different lives in two cities. Rent, taxes, transport and health coverage take their share before you decide what to save. An earlier GoBankingRates comparison used historical living-cost estimates. Its broader question still helps: what would that salary leave in your own household budget?
What a city comparison actually measures
A ranking starts with assumptions about a household, its taxes and the things it buys. Change those assumptions and the result changes. Some comparisons adjust purchasing power; others subtract estimated expenses. Those are different calculations. Before using a headline figure, find the study year and method. A modeled shortfall doesn't mean every resident earning that salary goes into debt.
New York makes the housing question hard to ignore
New York was the expensive end of the comparison in the earlier reporting. That is a historical result, rather than a current quotation for living there. The useful next step is more specific: find available homes near the job, price the space your household needs and include the costs of getting to work. A citywide average can't sign your lease.
Memphis illustrates the other side
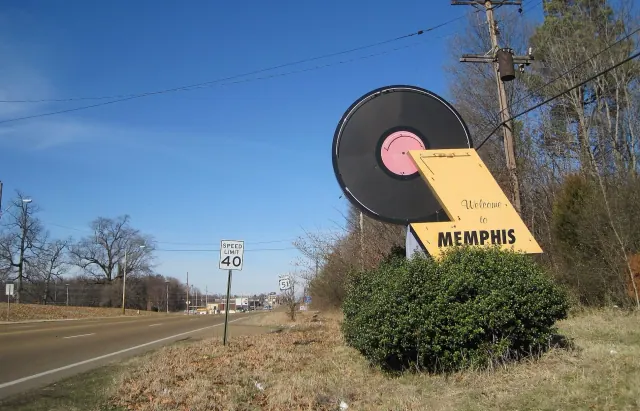
Memphis appeared at the affordable end of that historical comparison. Lower estimated costs can make an identical gross salary stretch further, but the savings aren't automatic. Your actual rent, job location, insurance and transport needs still matter. Compare the particular offer and neighborhood you would choose, including any change in household income, before treating a city's ranking as money in the bank.
A coastal-city ranking isn’t a personal budget
San Francisco, San Jose, San Diego and Boston featured among the expensive places in the earlier reporting. Each contains different housing markets and commuting choices. Someone sharing an apartment faces a different calculation from a household needing several bedrooms. Use the old list to identify questions about costs, rather than carry its dollar estimates into a new decision.
Price the neighborhood you can realistically use
Oakland, Los Angeles, Washington, Miami and Long Beach also appeared in the historical comparison. A cheaper home across town can bring a longer commute or another car into the budget. Look at the route and schedule as well as the address. A place that is affordable on a map may be difficult to use for the working hours you actually have.
Lower-cost cities still involve tradeoffs
The source also discussed El Paso, San Antonio, Tulsa and Oklahoma City as places where the modeled salary went further. That doesn't establish the best city for a particular worker. Family support, career options and access to services have value too. Start with the income you can actually earn there, then price the housing and transport arrangement you would realistically maintain.
Compare prices and earnings together
Wichita, Houston, Tucson, Jacksonville and Indianapolis rounded out other lower-cost examples in the archive. The names are useful prompts for research, not a current top-ten list. A move that reduces rent can still hurt your budget if pay falls by more. When a partner also works, compare both incomes and the likely timing of finding that second job.
Inflation and local prices answer different questions
Inflation measures how prices change over time. Regional price comparisons look at differences between places. The Bureau of Economic Analysis publishes regional price parities for a stated year, allowing comparisons against the national price level. Even that broad measure doesn't describe a particular family's bills. Keep the study year visible whenever you use a number from a cost-of-living comparison.
Borrowing costs belong in the calculation
A house price alone doesn't tell you the monthly payment. The interest rate, deposit, loan term and other housing expenses affect affordability. The original article cited the Federal Reserve's 2023–24 rate range; that isn't a current mortgage quote. Compare actual financing terms available for your transaction instead of inserting an old policy rate into a home-buying budget.
Remember the expense of moving
The first month in a cheaper city can be unusually expensive. Moving, travel, deposits and a gap between paychecks all require cash. Price those items separately from the ongoing monthly budget so they don't disappear inside an annual average. Also consider the time it could take for a lower monthly cost to recover those upfront expenses.
Make the offer fit your household
Before accepting a move, put take-home pay beside housing, food, transport, health coverage and your existing commitments. Use the employer's benefit details and real local quotes wherever possible. Then leave room for irregular expenses and savings. The salary headline tells you what the employer will pay. This second calculation tells you what that offer may let you do.