When your children move out, the household budget changes with them. Some bills may fall, while others barely move. You might still be helping with tuition, rent or a phone plan, and there may be visits home to account for. Before deciding what to do with the extra space, take a look at what has actually changed. The savings can be smaller, or larger, than you expected.
An Empty Nest Can Mean Different Things
The phrase usually describes parents or caregivers whose children no longer live at home. It says little about anyone’s finances. An adult child may still need support, return between jobs or live nearby and share expenses. Moving out is not a test of whether a parent raised someone successfully. Write down the arrangements your family actually has, including any support you intend to continue and when you will review it.
Give Yourself Time Before a Big Purchase
A quieter house can feel welcome, strange or both. You do not have to resolve those feelings by immediately renovating, moving or starting a business. It is reasonable to wait until the new routine feels more familiar. If you are considering a large expense, separate the practical reason for it from the urge to fill a newly empty room. Persistent distress deserves support in its own right, rather than a shopping project.
Sort Old Toys Together
Before selling or donating childhood belongings, ask whose they are and what the family wants to keep. A few favourite items may be worth more to you than their resale price. For the rest, look at completed sales of comparable items, not just ambitious asking prices. Allow for fees, packing and the time it takes to sell. Clearing a cupboard can be useful even when it produces very little money.
Price a Room Change Before a Remodel
A spare bedroom could become a workspace or guest room without major building work. Decide what you want the room to do, then compare the cost of a simple rearrangement with a renovation. Obtain quotes for substantial work and leave room for unexpected costs. A remodel may improve your enjoyment of a home, but you should not assume it will return every dollar when you eventually sell.
Check Whether the Books Have Resale Value
School books, picture books and novels can accumulate over many years. Ask a local second-hand bookshop what it accepts, or compare current offers from established buyers. Condition and edition matter, especially for textbooks. Do not assume an old online buyback programme still operates. If an ordinary paperback would cost more to ship than it earns, a local donation may make more sense. Check that the recipient actually wants those books first.
Look Through Records and CDs
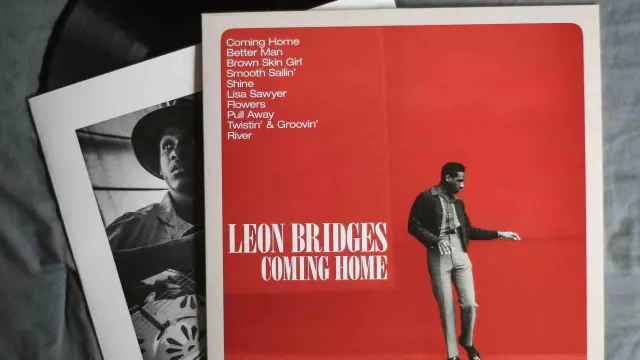
Some recordings have a resale market, but age alone does not make an album valuable. Check the edition and condition before setting a price. You may also want to keep music you enjoy owning: streaming catalogues and subscriptions can change. Selling a collection should be a choice, not a requirement of having more space. For a large collection, compare the convenience of a dealer’s offer with the work of individual listings.
Decide What to Do With Old Clothes
Separate clothing that family members want to keep from items suitable for resale, donation or recycling. Be realistic about condition and demand. Donation does not automatically produce a tax saving, and tax treatment depends on the rules and your circumstances. Keep records if you intend to claim a deduction and check the applicable requirements. The immediate benefit may simply be having a wardrobe you can use again without searching through years of storage.
Make a Plan for Unused Furniture
An adult child may want a desk or dresser, but their new home may not have room for it. Agree on what is staying before paying to move things. If you sell furniture, describe its condition accurately and arrange collection on terms you are comfortable with. Some pieces will cost money to remove. Include that possibility in the plan instead of counting every item as future income.
Compare the Full Cost of Downsizing
A smaller home is not automatically cheaper overall. Compare the likely sale proceeds with purchase costs, moving expenses, repairs, taxes, insurance and any association fees. A new mortgage can change the calculation substantially. Location, accessibility and proximity to people you rely on also matter. Run the numbers before listing the house, and leave time to consider whether the move would still appeal if the financial saving were modest.
Cancel What the Household No Longer Uses
Review streaming subscriptions, memberships, mobile plans and other recurring charges. Some may have been useful mainly to someone who has moved out. Check cancellation terms and ask before ending a service another family member still uses. Direct any actual savings toward a goal you have chosen, whether that is a reserve, debt repayment or retirement saving. Counting the same cancelled bill toward several goals makes the budget look better than it is.
Keep a Hobby’s Business Costs Visible
If you want to sell something you make or offer a service, start by estimating the costs. Materials, insurance, platform fees, tax obligations and your time all affect what is left. Test demand before spending heavily on equipment. It is also fine to enjoy a hobby without making it earn money. The next stage of family life does not need to come with a new business, and a financial reset can begin with a few smaller decisions.